

Credit Sesame: Grow your score
Credit Sesame, Inc.
- 4.7
- 32.05K Reviews
- 5.00M
- Downloads
- Free
- Price
Screenshots
Credit Sesame: Grow your score Pros and Cons
Pros
- Provides free credit score monitoring
- Offers personalized financial tips
- Includes identity theft protection
- Easy-to-use interface
- No credit card required to sign up
Cons
- Limited features in free version
- Occasional ads within the app
- Some users report slow updates
- Limited support for credit disputes
- Requires access to personal data
 Analysis by All-app
Money decisions rarely stay private within a household. A partner might be planning a car purchase, a roommate may be helping organize shared bills, or an adult child could be learning how credit works. In those moments, I find a personal credit app useful as a place for each person to understand their own situation—not as a shared family dashboard. Credit Sesame is built around an individual’s credit picture, so I would use it to prepare for a conversation, not to monitor someone else’s finances.
One household, separate credit lives
A practical scenario: my partner and I are comparing monthly expenses before applying for a loan. I can check my own score and review the guidance in the app, then discuss our budget together without assuming that our credit profiles are identical. That distinction matters: shared rent or household goals do not make credit records interchangeable. Each adult should make their own account decisions and review their own information.
This is also a useful boundary on a shared phone or tablet. I would avoid leaving a financial account open where another person could casually see it, and I would not treat a saved login as a household convenience. Credit details are personal even when the device is not. If several people want to use the service, it makes more sense for each to use their own account and sign out when finished than to pass one account around.
Set expectations before checking
The app is free to download, but that does not mean every financial product it presents is automatically right for you. Credit Sesame, Inc. develops this finance app, and its recommendations for cards or loans deserve the same careful comparison I would give any offer. I would check the full terms, fees, repayment schedule, and eligibility before acting, rather than choosing something simply because it appears beside a score or tailored tip.
There is another useful boundary: a score tool is a guide, not a promise about what a lender will decide. I would use the simulator to explore possible effects of a choice, then treat the result as an estimate rather than a guaranteed outcome. Before a major application, I would also review the relevant details directly with the lender and make sure the information I am relying on is current.
Coordinate without taking over
Credit Sesame can help make a money conversation more concrete. Instead of saying “we should probably pay down debt,” I can use the app’s guidance as a prompt to discuss which balances matter in our budget and what is manageable this month. The person whose account it is should remain in charge of decisions and access. A supportive partner can help compare options, but should not pressure someone to share a password or disclose a score.
For a household planning a move, a useful workflow is to check each person’s own credit information separately, write down questions, and then compare the household budget together. That avoids a common mistake: assuming one person’s score tells the whole story. It also keeps the app in its proper role—as a personal monitoring and learning tool—while the household makes shared plans using information everyone has chosen to discuss.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Age, privacy, and trust
The app carries an Everyone content rating, but that label is not a reason to hand a child access to an adult’s financial account. Credit information and borrowing decisions call for context and adult judgment. I would use it with an adult who is ready to manage their own finances, and explain that a score is only one part of financial health—not a grade on someone’s character or a shortcut to deciding whether they can afford something.
Trust matters just as much as convenience. A person may want help understanding a score while still keeping the account private, and that is a reasonable boundary. If a family member asks for help, I would sit beside them while they navigate their own account rather than signing in on their behalf or storing their credentials. That keeps the learning collaborative without turning a personal finance app into informal surveillance.
Get to Know Your Score
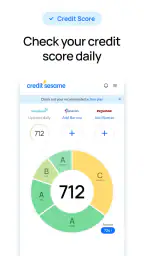
First things first, let’s talk about what Credit Sesame is all about. This app offers a free credit score check, and you don’t even need to whip out your credit card to sign up. I know, right? It’s like getting a free sample at the grocery store that actually fills you up. You simply download the app, create an account, and bam! Your credit score is ready for you to feast your eyes on.
Features That Make You Go "Wow"
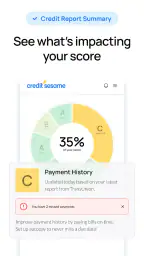
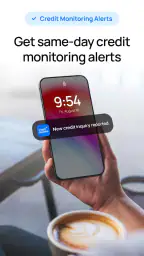
One of the standout features is the credit monitoring service. It’s like having a security camera on your credit report. The app sends you alerts whenever there’s a significant change, which I find super handy since I don’t always have time to keep tabs on it myself. Plus, there’s a personalized dashboard that breaks down your credit info in a way that even your grandma could understand.
Another neat feature is the credit score simulator. Ever wonder what would happen to your score if you paid off a chunk of your credit card debt? This tool lets you play around with different scenarios, so you can see how your actions might impact your score. It’s like having a crystal ball for your financial future.
Boosting Your Credit Made Easy
The app doesn’t just show you your score and leave you hanging. Oh no, it goes a step further by offering tailored advice on how to improve it. Whether it’s suggesting you pay down your balances or reminding you about upcoming due dates, it’s like having a little credit coach in your pocket.
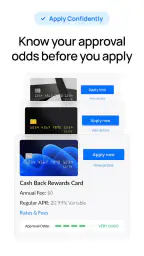
And if you’re looking to save some cash, Credit Sesame has your back there too. The app provides recommendations on credit cards and loans that could lower your interest rates. I’ve personally found this feature to be a game-changer, as it pointed me toward a credit card with much better terms than the one I was using.
Choosing the right role for the app
I see the strongest case for Credit Sesame when someone wants a low-friction way to keep an eye on credit between the bigger financial decisions. Its average rating is 4.7 from around 196,000 ratings, and it has been installed over 5 million times. That kind of reach makes it familiar to many users, but popularity alone shouldn’t replace checking whether its approach suits your needs.
Compared with a bank’s own credit feature, a dedicated app can put monitoring, explanations, and possible next steps in one place instead of making you search through several account menus. A bank may still be the better source for details about its own card, payment history, or lending decision. I would treat Credit Sesame as a useful overview and use the relevant financial institution when I need to resolve an account-specific question.
It also differs from checking a credit report directly. A report is the place to inspect underlying account details when you are checking for an error; a score-focused dashboard is more convenient for routine awareness and learning. My practical approach would be to use the app to notice changes and understand broad trends, then investigate any unfamiliar item through the appropriate reporting or financial institution channel rather than assuming an alert explains everything.
Make the tools useful, not distracting
The simulator is most helpful when I change one realistic assumption at a time. If I am weighing a debt payment, I would try the amount I could actually afford after essentials, rather than entering an optimistic figure just to see a more appealing projection. I would then compare that scenario with my monthly budget. This keeps the tool connected to a decision I can make, rather than turning it into a score-guessing game.
Alerts work best as prompts to investigate, not as a reason to panic. If a notice arrives, I would open the app, identify what changed, and decide whether I recognize it. If I do not, I would follow up through the relevant account provider or reporting channel. The value is in noticing a change sooner; the alert itself is not the same thing as a complete explanation or resolution.
Advice about paying down balances or due dates can also be turned into a simple routine: check the dashboard at a consistent point in the month, pick one action that fits the budget, and avoid making several financial changes at once just to chase a possible score movement. Credit improvement is not instant, and the app is more useful as a steady reference than as a daily scoreboard.
Where I would be cautious
The product is free, but it includes in-app purchases priced from $1.99 to $59.99 per item. I would review any purchase prompt carefully and decide whether it addresses a need I already have. The basic appeal is being able to check and manage credit without paying to download the app; that does not mean I would buy an add-on or accept a financial offer without comparing its cost and terms elsewhere.
Recommendations can save research time, but they can also make an app feel more like a shopping channel than a neutral notebook. I would compare a suggested card or loan with options from other providers, looking at the total cost rather than focusing only on a possible lower interest rate. If I am not planning to borrow, there is no need to apply just because an offer appears. For someone who wants no product suggestions at all, a bank’s limited score view or direct report access may feel more focused.
There is also a learning curve in knowing what a score can and cannot tell you. A favorable movement does not guarantee approval, and a dip does not by itself explain the cause. The dashboard can make information easier to digest, but I would not use it as a substitute for reading account statements, checking report details, or asking a lender about its criteria. That distinction is especially important when a deadline is close.
Who will get the most from it?
I would recommend giving it a try to adults who are building credit habits, want alerts rather than remembering to check manually, or are comparing possible ways to reduce borrowing costs. It may be particularly helpful if credit has felt opaque and a plain-language dashboard makes you more willing to look at it. The app is free, rated for Everyone, and its current version is 7.21.1; it was released on June 28, 2012, and requires OS 10 or later.
I would skip it if what you need is a joint household account, professional debt counseling, or a lender’s final answer about an application. It is not a replacement for a complete budget, and the person who dislikes financial product recommendations may prefer a more narrowly focused service. On a device that multiple people use, privacy habits matter too: keep financial access personal and do not assume the app provides household-sharing controls.
For someone wondering whether they need a paid subscription just to begin, the app itself is free to download, while optional in-app purchases may appear. For someone asking whether it can tell them exactly what will happen after paying down a balance, the simulator offers a way to explore a possible effect, not a guarantee. Those are the expectations I would set before relying on it: convenient visibility and guidance, with the final checks and choices still in your hands.
Final Thoughts
In a world where your credit score can seem like a mysterious beast, Credit Sesame offers a refreshing sense of transparency and control. It’s user-friendly, packed with features, and best of all, it’s free. Whether you’re looking to improve your score or just keep a closer eye on it, this app is definitely worth checking out.
So, if you’re curious about where you stand credit-wise or eager to boost your score, why not give Credit Sesame a try? It’s like having a financial advisor, a credit coach, and a savings guru all rolled into one handy app.
A sensible household role
For me, the best household use is individual review followed by a voluntary conversation: each person checks their own situation, then shares only what helps with a joint plan. That keeps credit management practical without blurring account boundaries. I would start with one concrete question—such as how to approach a balance or what an alert means—rather than trying to overhaul every financial habit at once.
Credit Sesame is a helpful companion for that kind of routine, especially when a clear dashboard makes it easier to pay attention. I would not call it a substitute for careful comparison or personal judgment, but as a free finance app for monitoring and learning, it earns a place on my shortlist. If you are comfortable keeping your account private and treating its suggestions as starting points, it is worth trying; if you want shared controls or purely institution-specific information, another route may fit better.
Frequently Asked Questions
What is Credit Sesame and how does it work?
Credit Sesame is a financial wellness app that provides users with free credit score monitoring and personalized financial advice. It helps users understand their credit score, factors affecting it, and offers tools to improve it. The app uses your credit report to suggest ways to increase your score, manage debt, and save money.
Is Credit Sesame really free to use?
Yes, Credit Sesame offers a free version that includes credit score monitoring, credit report analysis, and personalized recommendations. However, they also offer a premium service called Credit Sesame Pro, which provides additional features such as identity theft protection and enhanced credit monitoring for a monthly fee.
How often does Credit Sesame update my credit score?
Credit Sesame updates your credit score once a month. This allows you to track changes and see how your financial actions impact your score over time. While it provides a good overview of your credit health, it might not reflect real-time changes, which is something to consider for time-sensitive decisions.
Does using Credit Sesame impact my credit score?
No, using Credit Sesame does not impact your credit score. The app performs a 'soft' inquiry to access your credit information, which does not affect your score. This allows you to check your score as often as you like without worrying about any negative impact on your credit rating.
What security measures does Credit Sesame take to protect my data?
Credit Sesame takes several security measures to protect user data, including encryption and secure servers. They comply with financial industry standards to ensure your personal and financial information is safe. Additionally, they offer features like identity theft protection to help safeguard your identity and financial assets.


